Ask most people what their dental insurance actually pays toward a crown, and you’ll get a shrug, a guess, or a horror story about a bill that showed up weeks later. The honest answer is this: your plan might cover a meaningful chunk of a crown, or it might barely dent it, and the only way to know for sure is to check your specific benefits before you sit in the chair.
Coverage depends on your deductible, your remaining annual maximum, whether the tooth qualifies as restorative rather than cosmetic, and whether your dentist is in-network. None of that is universal. So before you book anything, the smartest move is asking your dental office to run a pre-treatment estimate so the numbers are on paper, not a guess.
Key Takeaways
- Dental insurance may cover part of a crown. Many plans treat crowns as major restorative care, but your actual benefit depends on your individual policy and whether you’ve met your deductible or annual maximum.
- Check your benefits before treatment. Ask about your crown insurance coverage, waiting periods, replacement limits, network status, and whether a dental crown pre authorization is required.
- Get a written estimate first. If you’re looking for dental insurance South Holland patients can use for restorative treatment, your dental office can often help verify benefits and submit a pre-treatment estimate so you know your expected out-of-pocket cost before booking.
Does Insurance Cover Dental Crowns?
Question: Does Insurance Cover Dental Crowns?
Answer: Here’s the thing nobody tells you upfront: “covered” and “free” are not the same word, even though patients treat them that way constantly. A lot of dental plans do provide some level of coverage for a restorative crown, meaning one placed because a tooth is cracked, decayed past the point of a filling, or weakened after a large root canal. But there’s no magic percentage that applies to every plan.
Some cover 50% of the “allowed amount” after your deductible. Some cover more. Some barely touch it if you’ve already burned through your annual maximum on other work earlier in the year.
There’s also a real distinction between what your insurer calls “covered” and what your dentist actually charges. Insurance companies negotiate an allowed amount, which can sit well below a dentist’s full fee, especially out-of-network. So a plan that “covers” major restorative work at 50% isn’t necessarily paying 50% of your bill. It’s paying 50% of their number. That gap is exactly where a lot of dental resentment gets born, and frankly, it’s a fair thing to be annoyed about.
The 7 Parts of Your Plan That Actually Decide Your Crown Cost
Reading a benefits summary feels like decoding a contract written by someone who hates you. It doesn’t have to be that hard once you know what you’re actually looking for.
- Is the crown a covered service at all? Look for language mentioning crowns or major restorative care. A plan covering fillings doesn’t automatically extend the same generosity to crowns.
- Your deductible. This is the amount you pay out of pocket before the plan starts contributing to certain services, and it resets annually.
- Your coinsurance. This is your share of the allowed amount after the deductible. If a plan pays 50% after deductible, you’re on the hook for the rest, based on the allowed fee, not necessarily the sticker price.
- Your annual maximum. Most plans cap what they’ll pay in a calendar year, often somewhere between $1,000 and $1,500, according to consumer research cited by the American Dental Association, which notes most plans function closer to a discount card than real financial protection for major work.
- Waiting periods. A brand new plan might make you wait months before major restorative work is covered at all.
- Frequency and replacement limits. If you already have a crown on that tooth, some plans won’t pay to replace it again for five to seven years.
- Network status. In-network dentists usually have negotiated fees, so your out-of-pocket cost can look very different depending on who’s doing the work.
Miss any one of those seven, and your estimate can be off by hundreds of dollars.
Why Plan Type Actually Matters
Not all “dental insurance” behaves the same way, and treating a PPO the same as a discount arrangement or a more restrictive managed plan is where people get blindsided. PPO plans generally give you more flexibility to see out-of-network providers, though you’ll usually pay more for that freedom since the plan reimburses less outside its network.
Other plan structures can be tighter, sometimes requiring you to stay within a specific list of providers to get any benefit at all. A plan card in your wallet doesn’t tell you any of this. You have to actually confirm the plan type, the network rules, the crown benefit percentage, your deductible status, and how much of your annual maximum is left before you can trust any number someone quotes you.
Preauthorization Versus a Pre-Treatment Estimate
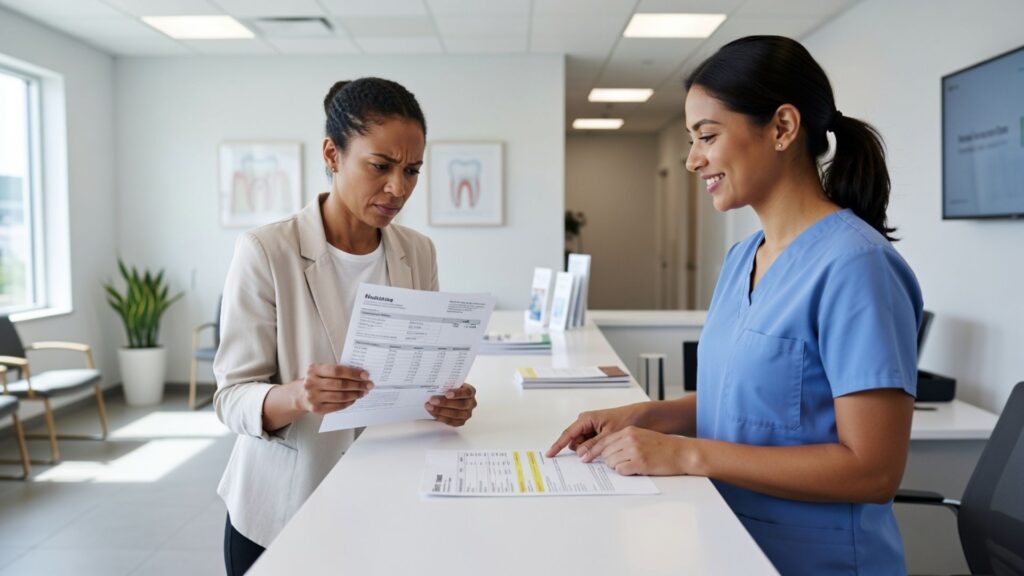
These two terms get used interchangeably, which causes more confusion than it should. A preauthorization, sometimes called precertification, is when your insurer reviews the proposed treatment beforehand and indicates whether it meets their plan’s criteria. A pre-treatment estimate, sometimes labeled predetermination, gives you a projected breakdown of what the plan may pay and what you’d likely owe, based on the information submitted.
Neither one is a guaranteed payment. Your final claim can still shift based on eligibility at the time of service, coding, remaining benefits, or plan rules that changed since the estimate went in. That said, having either document in hand before treatment beats walking in blind every single time.
What to Ask Your Insurer Before You Book
Call the number on your card, or dig through the member portal, and ask directly: Is a crown covered under my plan? What percentage applies? Has my deductible been met? How much of my annual maximum is left? Is there a waiting period or a replacement limit on this tooth? Does the plan require preauthorization? What’s the allowed amount for this procedure code? Write the answers down. A generic online summary of “dental benefits” almost never reflects your specific plan year, your specific tooth, or your specific history, and relying on it is how people end up disputing bills months later.
What a Crown Actually Costs Without Insurance
If you’re paying cash, the range is wider than most people expect. National figures compiled by GoodRx put a single crown somewhere between $800 and $2,500 out of pocket, with material choice driving most of that spread.
| Material | Typical Cost Range |
|---|---|
| Porcelain-fused-to-metal | $500 – $1,500 |
| All-porcelain or ceramic | $800 – $3,000 |
| Zirconia | $1,200 – $2,500 |
| Full gold or metal | $600 – $2,500 |
Crowdsourced patient data from CostHelper puts the average out-of-pocket spend for a standard porcelain-fused-to-metal crown around $1,093, which lines up with what most South Holland patients tend to report anecdotally. Out-of-network fees can run higher still, with an estimator showing a $1,100 to $2,000 baseline once you’re outside preferred pricing. And that’s before factoring in a build-up, a crown lengthening, or imaging, none of which are automatically bundled into a quoted crown fee.
Reading the Room on Insurance Frustration
I’ll be blunt here, because I think it matters. A lot of the anger people feel about crown pricing isn’t really about the dentist. It’s about the mismatch between what a benefit summary implies and what actually lands in the mail. Someone hears “I have insurance” and pictures real protection. Then they get a bill for $900 after insurance “helped,” and it feels less like coverage and more like a marketing label.
That reaction is completely reasonable. Dental insurance, as consumer advocates including Consumer Reports have pointed out, often behaves like a capped discount plan rather than comprehensive protection, and once you hit that annual maximum, insured and uninsured patients start looking financially similar.
Ways to Bring the Cost Down
None of this means you’re stuck accepting the first number you hear. A dental savings plan, sometimes marketed under a name like VantageOne, works differently than traditional insurance because it applies a flat treatment discount instead of running through deductibles and annual caps, which can make it genuinely useful for someone without employer coverage.
Financing through something like CareCredit or an American Express installment option can spread the monthly payment out instead of demanding the full crown cost upfront. And it never hurts to ask your provider directly whether a cash-pay discount applies, since eliminating insurance processing overhead sometimes lets a practice shave 15 to 30 percent off, according to guidance from Fair Visit Health. Dental schools offering supervised student care are another route worth exploring if your schedule allows for longer appointments.
Is the Crown Worth the Investment
A well-placed crown typically holds up for five to fifteen years under normal wear, based on clinical guidance from WebMD, which is a long runway compared to letting a cracked or heavily decayed tooth go untreated and risking an extraction later. The real question isn’t whether a crown is worth it in the abstract.
It’s whether you’re getting a transparent, itemized quote from a provider willing to walk you through material choice, lab fees, and what happens if your insurance estimate turns out lower than expected. A trustworthy office answers those questions before you commit, not after the bill lands.
FAQs About Dental Crown Insurance
Does dental insurance cover crowns? Many plans provide partial coverage for restorative crowns, but the percentage varies by plan, and your deductible, annual maximum, and network status all affect your final cost.
Does insurance cover a crown if I already have one on that tooth? It depends on the plan’s replacement limitation. Some plans won’t pay again for five to seven years, so check when the original crown was placed.
What is a dental crown preauthorization? It’s an insurer review completed before treatment that indicates whether the proposed procedure meets plan criteria, though it isn’t a guarantee of final payment.
How can I find out what a crown will actually cost me? Ask your dental office for a pre-treatment estimate and call your insurer directly about your deductible, coinsurance, and remaining annual maximum.
Does PPO insurance cover dental crowns? It can, but benefits differ by individual plan, and staying in-network usually lowers your expected out-of-pocket share.
Don’t let the word “covered” do the thinking for you. Gather your plan details, ask for a written pre-treatment estimate, and get the expected patient portion in front of you before you agree to anything. That’s the whole game.